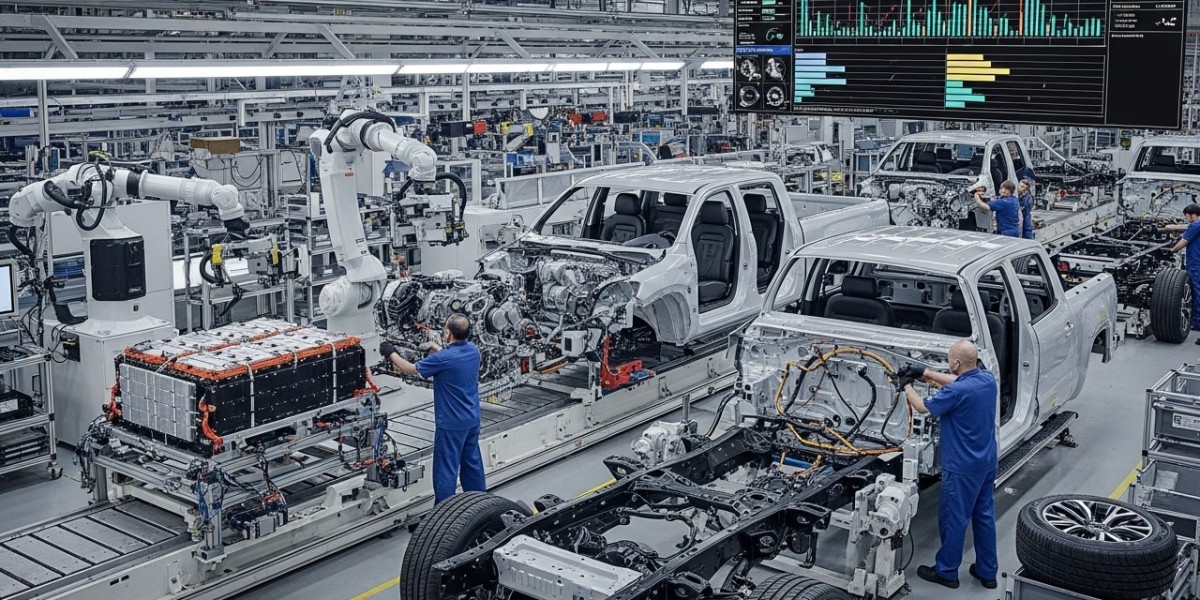

Understanding production expenses is essential for businesses that want to manufacture products efficiently and remain competitive. Before starting a manufacturing project, companies need to evaluate the resources, materials, labor, equipment, and processes required to produce their goods. Accurate manufacturing cost estimation helps businesses prepare realistic budgets, determine suitable pricing strategies, and make informed production decisions. manufacturing cost estimation is a useful starting point for exploring manufacturing requirements, production planning, and the factors that influence the overall cost of making a product.
Understanding Manufacturing Cost Estimation
Manufacturing cost estimation is the process of calculating the expected expenses involved in producing a particular product or component. It considers both direct and indirect costs associated with production activities.
Direct costs are expenses that can be directly connected to manufacturing a specific product. These generally include raw materials, production labor, and certain manufacturing supplies. Indirect costs support production operations but cannot always be assigned to an individual product. Examples include factory rent, equipment maintenance, utilities, and administrative expenses.
Understanding these categories helps businesses develop a more complete picture of their production requirements. It also reduces the possibility of overlooking important expenses when preparing a manufacturing budget.
1. Calculate Raw Material Costs
Raw materials are among the most significant expenses in many manufacturing operations. The quantity, quality, availability, and market price of materials can directly influence production costs.
Start by identifying every material required to manufacture the product. Calculate the quantity needed for each production unit and multiply it by the relevant purchase price. Remember to consider additional material requirements caused by cutting waste, defects, or processing losses.
Material prices may change because of market conditions, transportation expenses, supplier availability, and purchasing volumes. Businesses should therefore obtain updated supplier quotations rather than relying entirely on historical prices.
Comparing different material options can also reveal opportunities to reduce expenses while maintaining the required product performance and quality.
2. Estimate Labor Expenses
Labor costs include the wages and related expenses associated with employees involved in manufacturing. These may include machine operators, technicians, assembly workers, production supervisors, and quality-control personnel.
To estimate labor expenses, determine how many working hours are required to manufacture each product. Multiply the estimated production time by the relevant hourly labor rate.
Businesses should also consider employee training, overtime, benefits, and other applicable employment expenses. Production efficiency is another important factor because inexperienced workers or inefficient processes may increase the time required to complete manufacturing activities.
Accurate labor estimates help businesses understand staffing requirements and identify opportunities to improve production workflows.
3. Evaluate Machinery and Equipment Costs
Manufacturing equipment represents another important cost category. Depending on the production method, businesses may need CNC machines, injection molding equipment, cutting tools, assembly systems, or specialized machinery.
Consider the purchase price, installation expenses, operating costs, maintenance requirements, and expected equipment lifespan.
For existing machinery, depreciation can be included when calculating production expenses. For new equipment, businesses should evaluate whether purchasing, leasing, or outsourcing production offers the most practical financial arrangement.
Equipment utilization also matters. Machines that remain unused for extended periods can increase the cost allocated to each manufactured unit.
4. Include Overhead and Operating Expenses
Manufacturing overhead includes expenses that support production but are not directly assigned to individual products. These costs are necessary for maintaining factory operations.
Common overhead expenses include:
Facility expenses: Factory rent, electricity, water, heating, and general maintenance.
Operational expenses: Equipment servicing, quality inspections, production management, and indirect labor.
Businesses should establish a consistent method for allocating overhead expenses across products or production activities. This makes product costing more transparent and supports better financial planning.
5. Consider Manufacturing Methods and Production Volume
The selected manufacturing process can significantly influence total production expenses. CNC machining, injection molding, casting, sheet metal fabrication, and 3D printing each have different setup requirements, equipment costs, material consumption, and production speeds.
Production volume is equally important. Some processes require substantial initial investment but offer lower unit costs when manufacturing large quantities. Others are more economical for prototypes, customized components, or smaller production runs.
Businesses should compare different manufacturing methods before finalizing their production plans. Evaluating tooling costs, processing time, material waste, and expected output can help identify the most suitable approach.
6. Account for Quality Control and Additional Expenses
Quality control should be included in every manufacturing budget. Inspection, testing, calibration, and product verification help ensure that finished goods meet the required specifications.
Other expenses may include packaging, storage, transportation, product finishing, and supplier management. Depending on the industry, businesses may also need to account for certification, regulatory compliance, and specialized testing.
Including these expenses creates a more realistic estimate and reduces the risk of unexpected financial pressure during production.
7. Review and Update Cost Estimates
Manufacturing estimates should be reviewed whenever important production conditions change. Material prices, labor rates, equipment availability, supplier quotations, and production schedules can all affect the final cost.
Businesses can use spreadsheets, costing software, and enterprise resource planning systems to organize financial information. Comparing estimated expenses with actual production costs also helps identify inaccurate assumptions and improve future budgeting.
Maintaining updated records supports better purchasing decisions and makes it easier to evaluate manufacturing performance over time.
Conclusion
Accurate manufacturing cost estimation is essential for successful production planning and financial management. By evaluating raw materials, labor, equipment, overhead, manufacturing methods, and quality-control requirements, businesses can develop realistic production budgets and make informed operational decisions. Regularly reviewing estimates also helps organizations respond to changing market conditions and control unnecessary expenses. A structured approach to manufacturing costing supports efficient resource management, competitive pricing, and sustainable business growth.